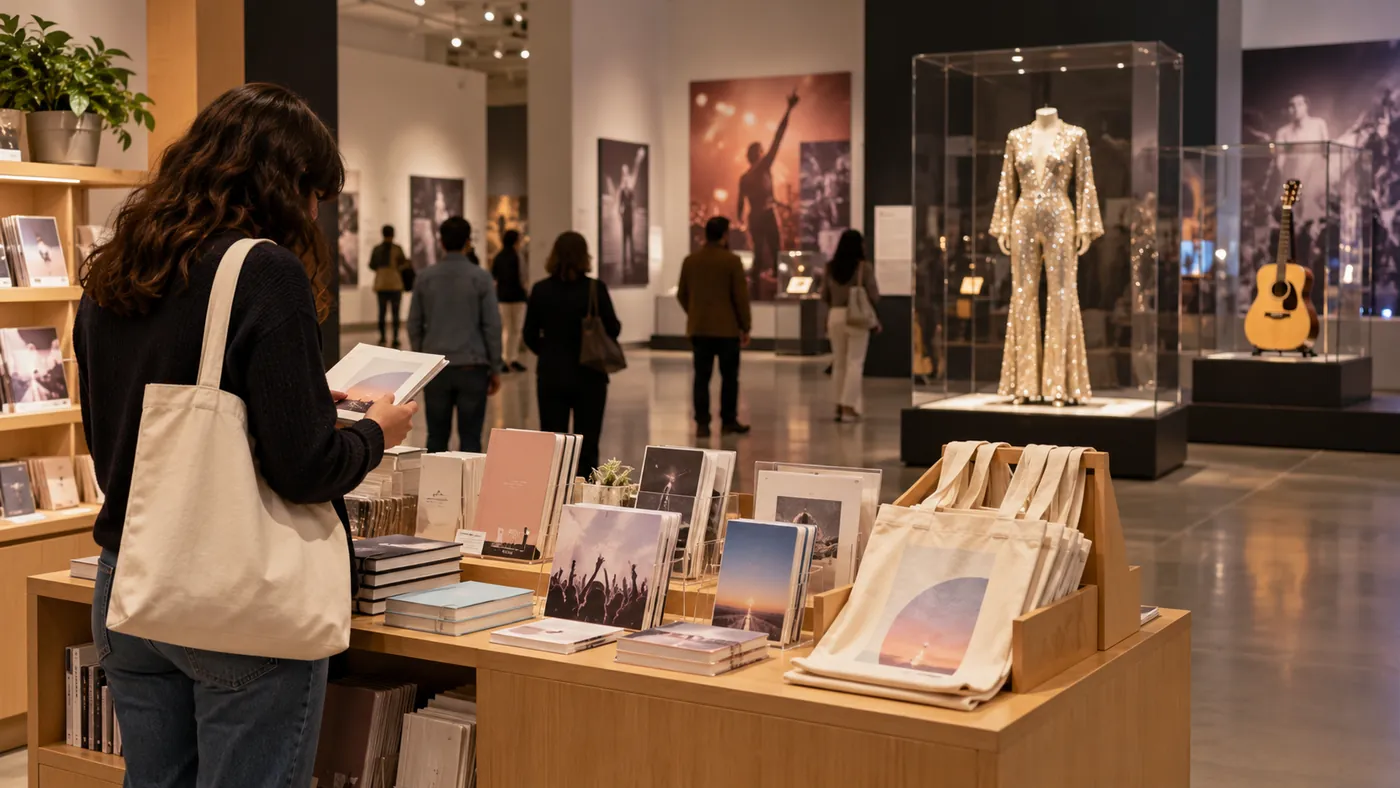
The Songbook Trail at London’s V&A museum, displaying global pop star Taylor Swift’s outfits and instruments, closed successfully after attracting about 250,000 visitors over seven weeks in summer 2024. In particular, the museum announced in its annual report that related merchandise alone generated no less than £1.1 million in sales, approximately KRW 1.9 billion.
A model that generates substantial traffic through a free exhibition and earns revenue from merchandise sales is the ideal income structure many planners dream of. From an event planner’s perspective, however, using these impressive figures directly as the budget basis for the next event is highly risky. As the settlement and debriefing guidelines in the “Case Article Review” file also warn, the traffic of 250,000 visitors and the £1.1 million in sales are fundamentally different datasets that need to be analysed separately.
1. Decoupling metrics: do not estimate spend per customer from visitor numbers
One of the most common statistical mistakes is arbitrarily calculating spend per customer by saying, “Dividing £1.1 million by 250,000 people means each person spent about £4.40.”
- The mystery of purchase conversion: A free exhibition is also open to visitors with no intention of opening their wallets. The report contains neither the number of people who actually paid for merchandise nor purchase records for individual visitors. It is highly likely that a small number of devoted fans spent hundreds of pounds while most general visitors bought nothing. Without purchase-conversion data that compares the precise number of paying customers from POS records with total admissions, any estimate of spend per customer is merely a vanity figure.
2. Revenue is not profit
The dazzling sales figure of £1.1 million does not mean that the same amount of net profit accumulated in the museum’s coffers.
- Subtract back-end costs: Behind enormous merchandise sales sit substantial IP royalties for a global pop star, the cost of goods sold (COGS), on-site retail labour and payment-processing fees.
- The invisible invoice: dead stock: Some items may have sold out during the seven weeks. Yet storage and disposal costs for unsold stock left in the warehouse after the event fall entirely on the organiser as losses. Planners need to assess business viability against the cool-headed net-profit figure remaining after all these deductions, rather than the glamorous gross-sales total.
3. Two entirely different KPIs: traffic versus sales
Through this display, the V&A attracted more than 100,000 first-time visitors to the museum.
- Separate the objectives: Bringing in a free audience needs to be treated as a long-term customer-acquisition cost for the museum, while merchandise sales are the result of short-term monetisation. The two must not be bundled together into a verdict of “a successful commercial exhibition.” From the planning stage, clearly declare the primary KPI: is this a marketing exhibition funded to reach new audiences, or a profit-oriented exhibition focused strictly on retail earnings?
4. A four-stage settlement protocol for free exhibitions with paid merchandise
When planning an event that must make up its revenue through merchandise or ancillary product sales without charging admission, the practical team needs the following four stages.
| Stage | Working standard |
|---|---|
| [Stage 1: Split budgets and objectives] | Manage completely separate profit-and-loss statements (P&Ls) for the operating budget, or sunk cost, of creating the free exhibition space and the retail budget for producing and selling merchandise. |
| [Stage 2: Work backwards from the break-even point (BEP)] | Calculate the net-profit margin after deducting each product’s production cost, sales fees and intellectual-property royalties, then determine the minimum quantity that must be sold to cover exhibition operating costs. |
| [Stage 3: Build a purchase-conversion tracking system] | Compare admission-counting sensor data at the gate with the merchandise shop’s POS transaction counts every day to quantify purchase conversion by day of the week and time of day. |
| [Stage 4: Complete the final debrief with remaining stock included] | Go beyond announcing total sales immediately after closing. Three months later, close and sign off the final settlement report, including the sell-through of remaining stock through channels such as online sales and the cost of disposal. |
Planner’s note: cool-headed subtraction carries the weight of the numbers
The impressive sales coverage distributed to the press after an event can make a planner feel proud. Yet before celebrating the substantial sum deposited in the account with champagne, the planner’s first task is to pick up a calculator and begin unsentimental subtraction.
The small, unimpressive number that remains only after royalties have been paid, goods have been paid for and the boxes left in the warehouse have been written down to zero: only a planner who honestly faces that painful, unvarnished net-profit figure can plan the next event to fill both visitors’ hearts and the company’s coffers.
Conditions for applying this elsewhere
The figures cover seven summer weeks in 2024, not annual merchandise revenue or profit. Do not infer conversion or spend per buyer from attendance.
Information not established
Product costs, rights fees, buyer counts, visitor-linked purchases, conversion, the display’s profit and actual inventory procedures were not established.
Reference material
- V&A · Official Taylor Swift | Songbook Trail information: 27 July–8 September 2024, 13 stops, free entry without reservations and displays across permanent galleries
- V&A Annual Report and Accounts 2024–25 · page 12 on visitors and page 36 on related merchandise sales; accounting period 1 April 2024–31 March 2025
Next tasks and related resources
Defined related products, units sold, returns, remaining stock, actual costs and separate audience results
Related practical guides
Event Budget and Conditional Cost Management
An event budget contains both committed costs and amounts that depend on decisions still to be made. Mark the difference and update the forecast whenever those conditions change.
Read guideHave a correction or additional evidence? Request a correction